Market overview of the Image Signal Processor Market
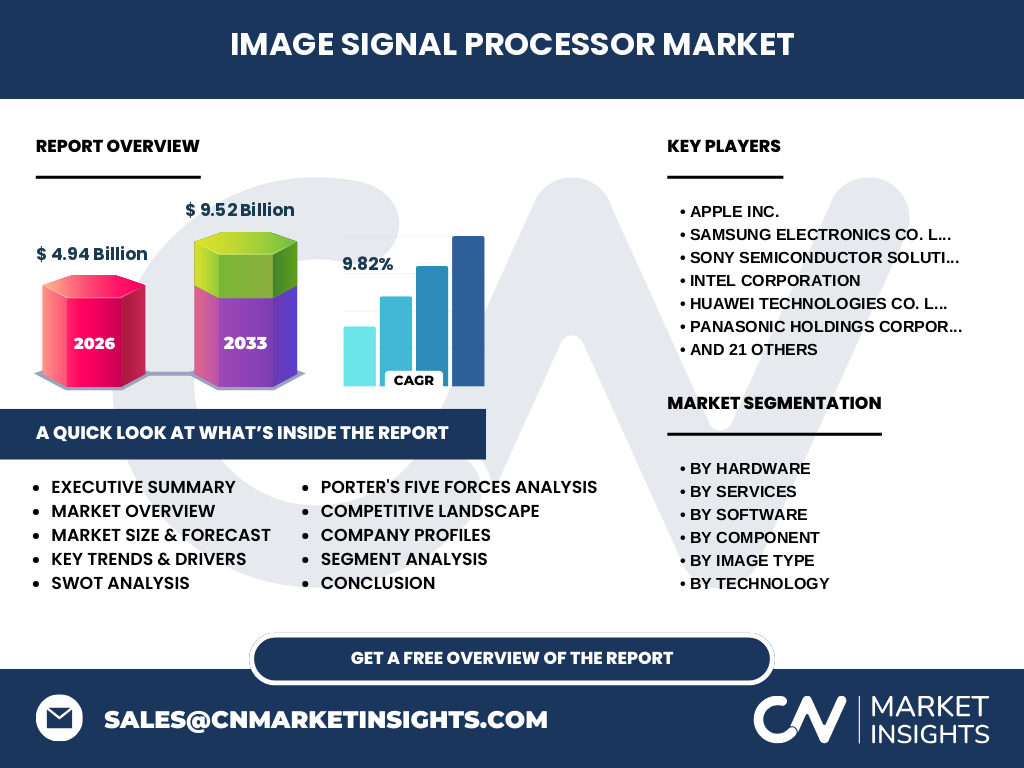
Our analysis indicates that the Image Signal Processor Market is valued at 4.94 Billion in 2026, establishing a critical foundation for digital imaging systems. This sector encompasses advanced silicon architectures that manipulate raw image data from sensors into refined visual outputs. Key innovators like Sony Semiconductor Solutions Corporation and Qualcomm Technologies Inc. drive industry significance by enabling high-resolution computational photography across mobile, automotive, and industrial domains.
Structural Growth Drivers and Market Constraints
The market thrives on surging demand for multi-camera mobile arrays and ADAS sensors, though supply chain bottlenecks for advanced semiconductor raw materials like high-purity silicon present persistent hurdles. NVIDIA Corporation and Texas Instruments Incorporated navigate these logistical constraints by optimizing fabrication yields. Meanwhile, stringent automotive safety regulations enforced by bodies like the UNECE mandate ultra-low latency processing, shaping deployment priorities worldwide.
Emerging trends and growth patterns in the Image Signal Processor Market
The sector is witnessing a decisive shift toward edge-AI integration, where hardware accelerators embedded by firms like Ambara Inc. execute neural network algorithms directly on-chip. This evolution drastically reduces bandwidth consumption for security and surveillance applications. Arm Holdings plc is capitalizing on this trend by licensing energy-efficient architectures tailored for localized pixel processing and real-time noise reduction software.
COVID-19 impact analysis and recovery trajectory
Pandemic-induced supply chain disruptions severely constrained fabless semiconductor output across major logistical hubs in East Asia. However, the post-pandemic recovery trajectory proved robust, accelerated by remote-work hardware upgrades and surging medical imaging demands. Manufacturers diversified wafer sourcing through partners in Taiwan and South Korea, mitigating future vulnerabilities and securing a steady climb toward upcoming valuation milestones.
Competitive Benchmarking and Market Concentration
Market concentration remains moderately high, dominated by fabless giants and integrated device manufacturers. Apple Inc. and Samsung Electronics Co. Ltd. leverage proprietary silicon design to maintain device differentiation. Meanwhile, specialized players like OMNIVISION and onsemi focus on high-performance sensor-ISP co-design, capturing vital design wins in automotive and medical sectors where precision optics and stringent quality compliance are non-negotiable.
Executive summary of the Image Signal Processor Market report
Our comprehensive research demonstrates that the Image Signal Processor Market is projected to surge from 4.94 Billion in 2026 to 9.52 Billion by 2033 at a robust 9.82% CAGR. Growth is heavily anchored in hardware innovations and software-defined imaging algorithms. Stakeholders must prioritize edge AI integration and strategic fab partnerships to capture high-margin opportunities across automotive and smartphone verticals.
Market forecast from 2027 to 2033
The data suggests sustained expansion, scaling the market from its 4.94 Billion baseline in 2026 to an impressive 9.52 Billion by 2033, maintaining a steady 9.82% CAGR throughout the forecast window. This trajectory reflects accelerating adoption in autonomous driving systems and ultra-high-definition industrial machine vision. Companies investing proactively in SIMD and MIMD architectures will capture disproportionate revenue shares.
Segmentation analysis across hardware, software, and services
The ecosystem breaks down by Component into Hardware, Software, and Services. Hardware includes Processing Units, Sensors, Memory Devices, Interface Modules, and Power Management Units. Software encompasses Image Processing Algorithms, Noise Reduction, Color Correction, Enhancement, and Compression software. Services feature Integration, Consulting, Maintenance, Support, and Development. MediaTek Inc. and NXP Semiconductors N.V. heavily leverage these hardware-software synergies to optimize computational throughput.
Geographic distribution and regional market analysis
Regional performance varies based on localized manufacturing ecosystems and regulatory strictures. Asia-Pacific dominates production volume, anchored by foundries in Taiwan and consumer electronics assembly lines in China and South Korea. North America captures substantial value through software algorithm development and fabless semiconductor design by enterprises like Marvell Technology Inc. and Microchip Technology Incorporated, catering to high-end defense and medical imaging applications.
In-depth regional review of key markets
In North America, strict FDA guidelines for medical imaging drive demand for ultra-precise sensor interfaces. Conversely, the Asia-Pacific market thrives on high-volume smartphone manufacturing by original equipment manufacturers. European markets prioritize automotive safety standards mandated by the European Commission, prompting Tier-1 suppliers to integrate advanced ISP solutions that ensure reliable machine vision in adverse weather conditions.
Strategic positioning of leading companies
Industry leaders maintain distinct competitive moats. Sony Semiconductor Solutions Corporation commands high-end image sensor integration, while Qualcomm Technologies Inc. dominates mobile Snapdragon platforms with advanced proprietary ISPs. Canon Inc., Fujifilm Holdings Corporation, and Nikon Corporation leverage decades of optical expertise to refine internal processing pipelines for professional digital cameras, insulating their margins against commoditization.
Porter's Five Forces analysis of the industry
Supplier power is moderate due to high capital requirements for semiconductor fabrication foundries operated by companies like TSMC. Threat of new entrants remains low owing to steep R&D barriers and complex intellectual property landscapes. Competitive rivalry is intense, driven by rapid innovation cycles in smartphones and automotive ADAS, forcing firms like Socionext Inc. and Ambarella Inc. to continually push performance boundaries.
SWOT analysis of the Image Signal Processor Market
Strengths include deeply entrenched proprietary silicon architectures and advanced computational photography software. Weaknesses involve high vulnerability to silicon wafer supply disruptions and soaring R&D costs. Opportunities abound in autonomous vehicle deployment and medical diagnostic imaging upgrades. Threats stem from macroeconomic inflationary pressures impacting consumer electronics purchasing power across mature regional markets.
Value chain analysis from raw materials to end-users
The value chain initiates with high-purity silicon extraction and chemical vapor deposition materials. Mid-stream processes involve wafer fabrication, architectural design by firms like Arm Holdings plc, and packaging. Downstream distribution flows through Original Equipment Manufacturers and Aftermarket channels. STMicroelectronics N.V. and Renesas Electronics Corporation manage crucial mid-stream touchpoints, ensuring efficient delivery to end-use sectors.
Investment insights and high-potential areas
High-potential capital allocation centers on edge-AI image processing accelerators and specialized automotive-grade silicon compliant with ISO 26262 safety standards. Investors should monitor agile fabless innovators such as Nextchip Co. Ltd. and Pixelplus Co. Ltd. that target niche surveillance and automotive blind-spot detection markets, offering superior growth potential compared to saturated legacy consumer segments.
Conclusion and key takeaways
The Image Signal Processor Market represents a vital, high-growth technology frontier poised to reach 9.52 Billion by 2033. Driven by a robust 9.82% CAGR from 2026, success in this ecosystem requires balancing hardware efficiency with sophisticated algorithmic software. Strategic partnerships across the semiconductor supply chain will separate market leaders from laggards.
Research methodology and data triangulation
Our baseline estimates are rigorously triangulated by combining customs trade registry data, primary stakeholder interviews with semiconductor executives, and secondary macroeconomic indicators from global trade bodies. We reconcile shipment volumes reported by key industry participants like Altek Corporation and THine Electronics Inc. with foundry capacity reports to ensure unmatched accuracy in our market sizing models.
Scope of the report and coverage parameters
This report evaluates the global market across hardware, software, and service components, spanning applications from smartphones to industrial machine vision. Geographic scope covers North America, Europe, Asia-Pacific, Latin America, and the Middle East & Africa. Excluded from this specific valuation are display-driver integrated circuits and generic application processors lacking dedicated image signal processing pipelines.
Recent developments and strategic industry moves
Recent market dynamism is highlighted by aggressive R&D investments and cross-industry joint ventures aimed at enhancing computational photography. Huawei Technologies Co. Ltd. and Panasonic Holdings Corporation have announced strategic initiatives focusing on proprietary imaging algorithms, while emerging players secure critical funding to accelerate automotive-grade silicon prototyping and commercial rollouts.